Do the website work you used to send to the agency.
New product pages, campaign landing pages, a Spanish section, a refresh of the whole checking area. Your team asks for it in plain English. An AI assistant drafts it on your site, in your bank's voice, and checks it against the banking rules. Compliance approves it before anything goes live.
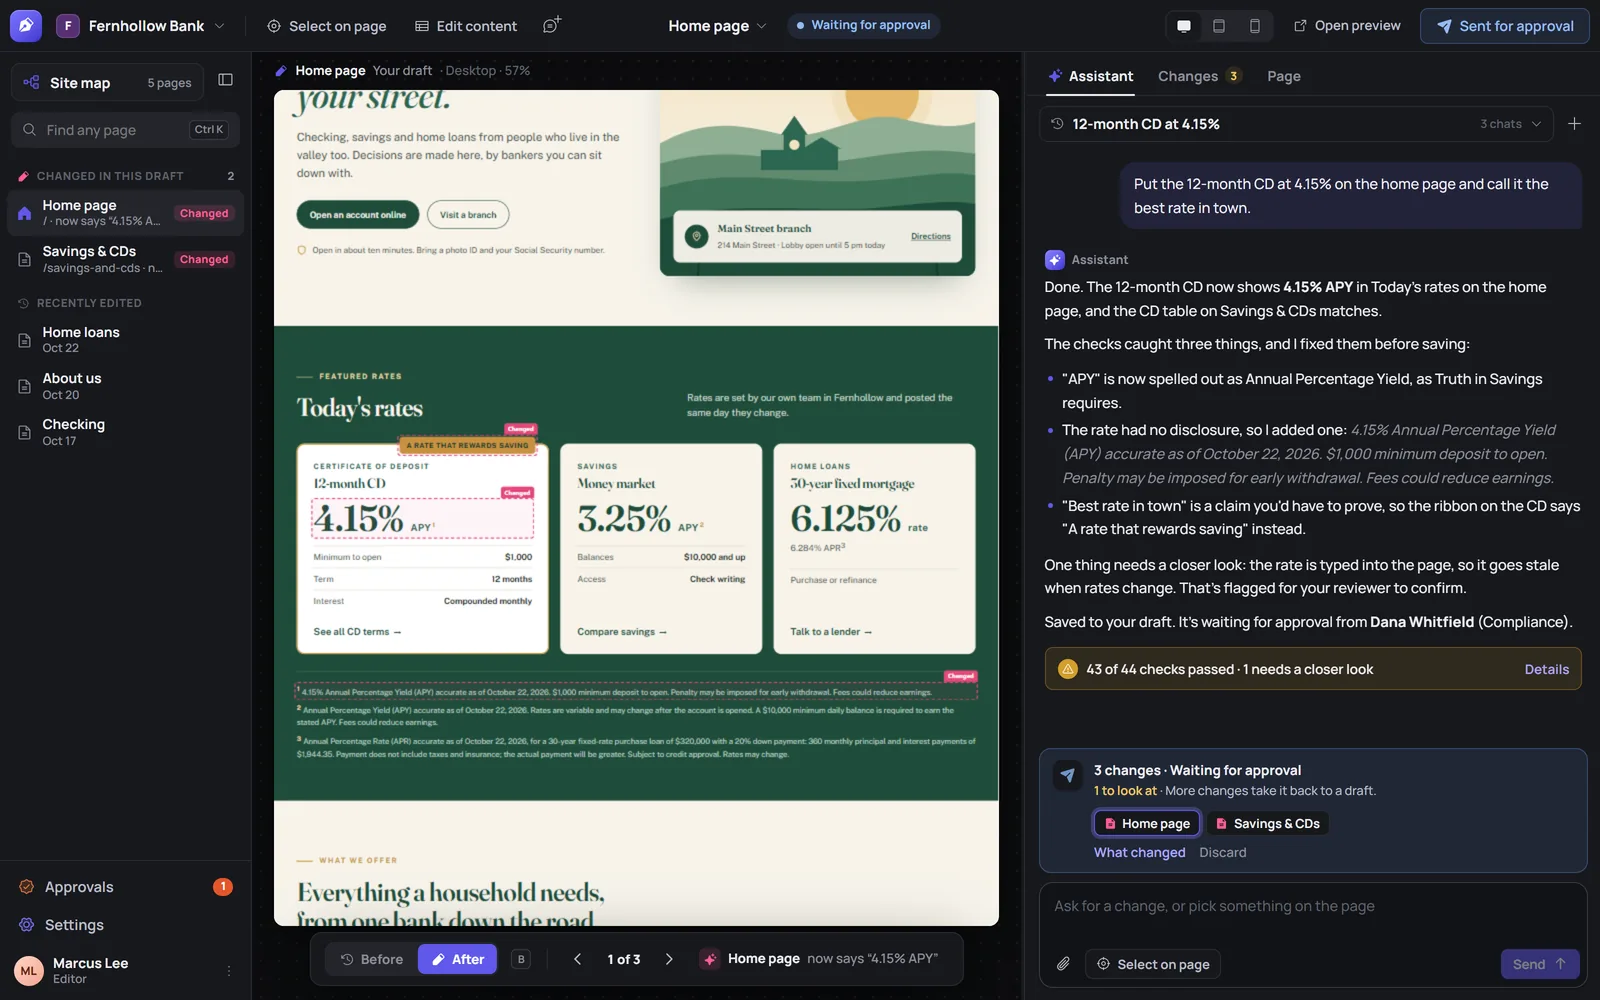
- Fixed: "APY" spelled out as Annual Percentage Yield, rate disclosure added.
- Fixed: "Best rate in town" reworded. It's a claim you'd have to prove.
- For your reviewer: a rate typed into the page. Dana in compliance confirms it.
The work that used to be a project.
Most bank websites can already take a new rate. What they can't do is grow: a new page means a brief, an estimate, design rounds, a PDF for compliance to mark up, and an invoice. So the site stays the way the agency left it.
A landing page for the spring HELOC campaign
A page for first-time homebuyers
Spanish versions of the deposit pages
Rework the checking section
Fix what the accessibility audit found
It writes like your bank, not like a chatbot.
It reads your voice from the pages you already have: how you sound, what you call yourselves and the people you serve, the words you never use. You look it over and adjust it, then name the people your pages are for. Every draft follows both, and you change whatever you'd say differently.
Warm, plain and neighborly, with steady local pride. Keep sentences short, at an everyday reading level. Say "we" and "our" for the bank, and speak to the reader as "you". Use contractions, and skip exclamation marks.
"We're not trying to be the biggest bank in the state. We're trying to be the one you'd recommend to your sister."
customersyoufinancial institutionbankregionthe valley
- First-time homebuyerCalm and step by step. Explain each term. Make it easy to reach a person.Grade 7
- Retiree moving moneyReassuring and practical. Answer what they'd worry about: safety, cost, control.Grade 8
- Small business ownerDirect. Upfront about costs. Show who they'll work with.Grade 10
Unlock the door to your dream home! At Fernhollow, we leverage innovative solutions to make your homeownership journey seamless and hassle-free, with the best rates in town.
Buying your first home comes with a lot of new words and a lot of paperwork. We'll walk you through both, one step at a time. You'll work with the same loan officer from your first question to closing day, and you can call or stop by whenever something isn't clear.
Your team asks. The assistant drafts. People decide.
Ask
Your marketing teamDescribe the page or the change in plain English. Point at anything on the page, or paste a screenshot of what you have in mind.
Draft
AI assistantBuilds the draft on your site, in your brand. You see it in a live preview on desktop, tablet and phone, and keep asking until it's right.
Check
AI assistantRuns 44 checks. Fixes the clear-cut problems before saving, like a missing disclosure, and says what it changed. Flags the judgment calls for a person.
Approve
Your compliance reviewerSees exactly what changed, with the reasons. Approves, or sends it back with a note. Nothing goes live until someone does.
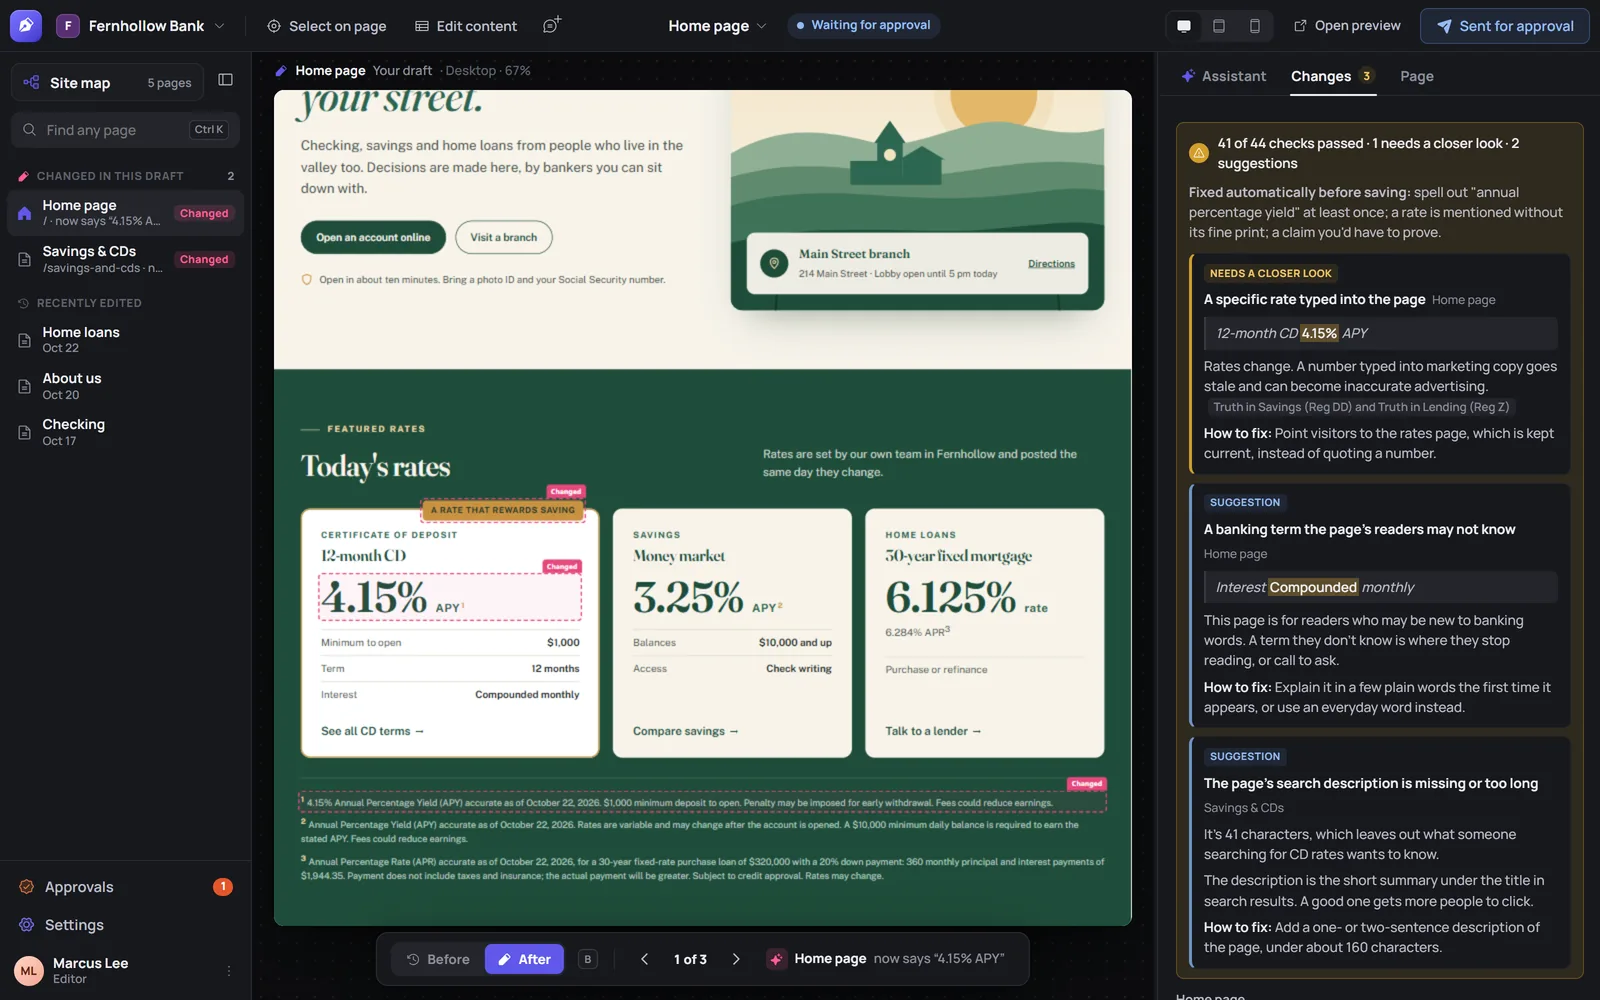
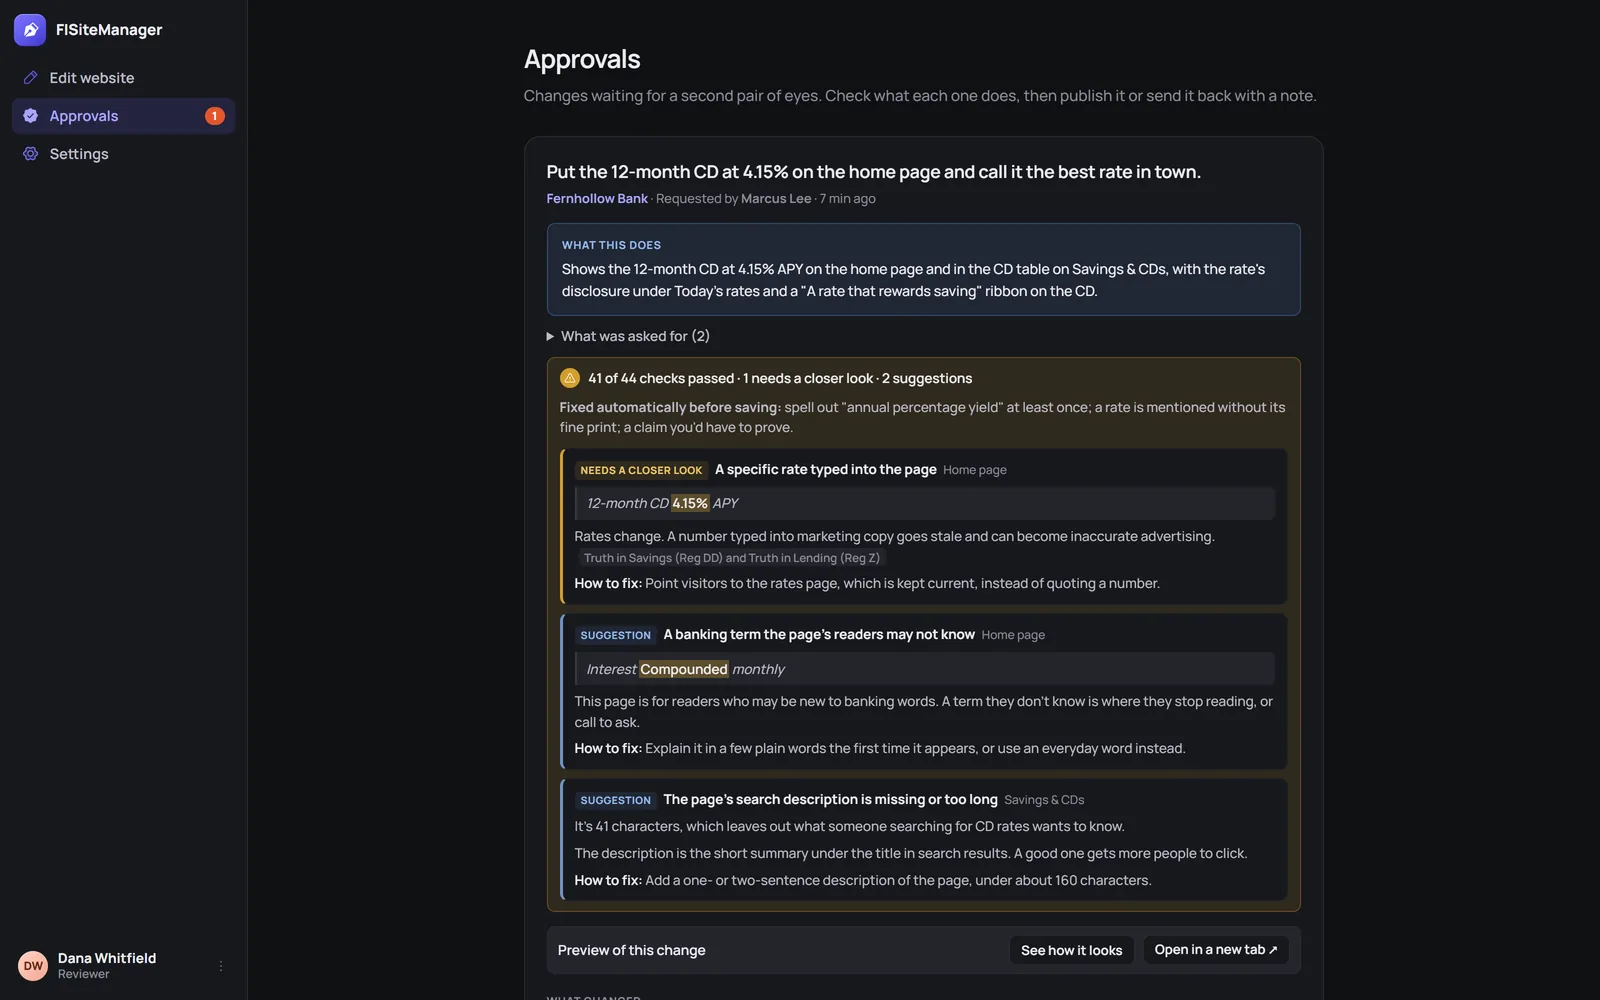
They still sign off. They stop catching the same mistakes.
The review your compliance officer does by hand today, comparing the page against the rate sheet and the disclosure rules, happens before the draft ever reaches them. What's left is the part that needs their judgment.
Fixed before saving (3)
"APY" spelled out. Disclosure added. "Best rate in town" reworded as "a rate that rewards saving", since it's a claim you'd have to prove.
A specific rate typed into the page.
Rates change, and typed numbers go stale. Sent to the reviewer to confirm.
| Check | Rule | What happens |
|---|---|---|
| APY and APR spelled out with the rate | Truth in Savings, Truth in Lending | Must fix |
| A rate without its disclosure | Truth in Savings, Truth in Lending | Must fix |
| Promising approval or a guaranteed rate | UDAAP, fair lending | Must fix |
| A required notice was removedEven when the edit was about something else | Deposit insurance, fair housing | Must fix |
| Loan terms that trigger more disclosure | Truth in Lending (Reg Z) | Needs a closer look |
| Calling an account "free" | Truth in Savings | Needs a closer look |
| Deposit insurance noticeMember FDIC for banks; NCUA for credit unions, and the other one flagged | FDIC Part 328, NCUA Part 740 | Needs a closer look |
| Equal Housing on home lending pagesEqual Housing Lender for banks; Equal Housing Opportunity for credit unions | Fair Housing Act | Needs a closer look |
| "Customers" on a credit union site | Members, not customers | Suggestion |
Plus accessibility, broken links, claims you'd have to prove, reading level and more. The checks help catch common problems; they aren't legal advice, and your compliance team decides. See all 44 checks
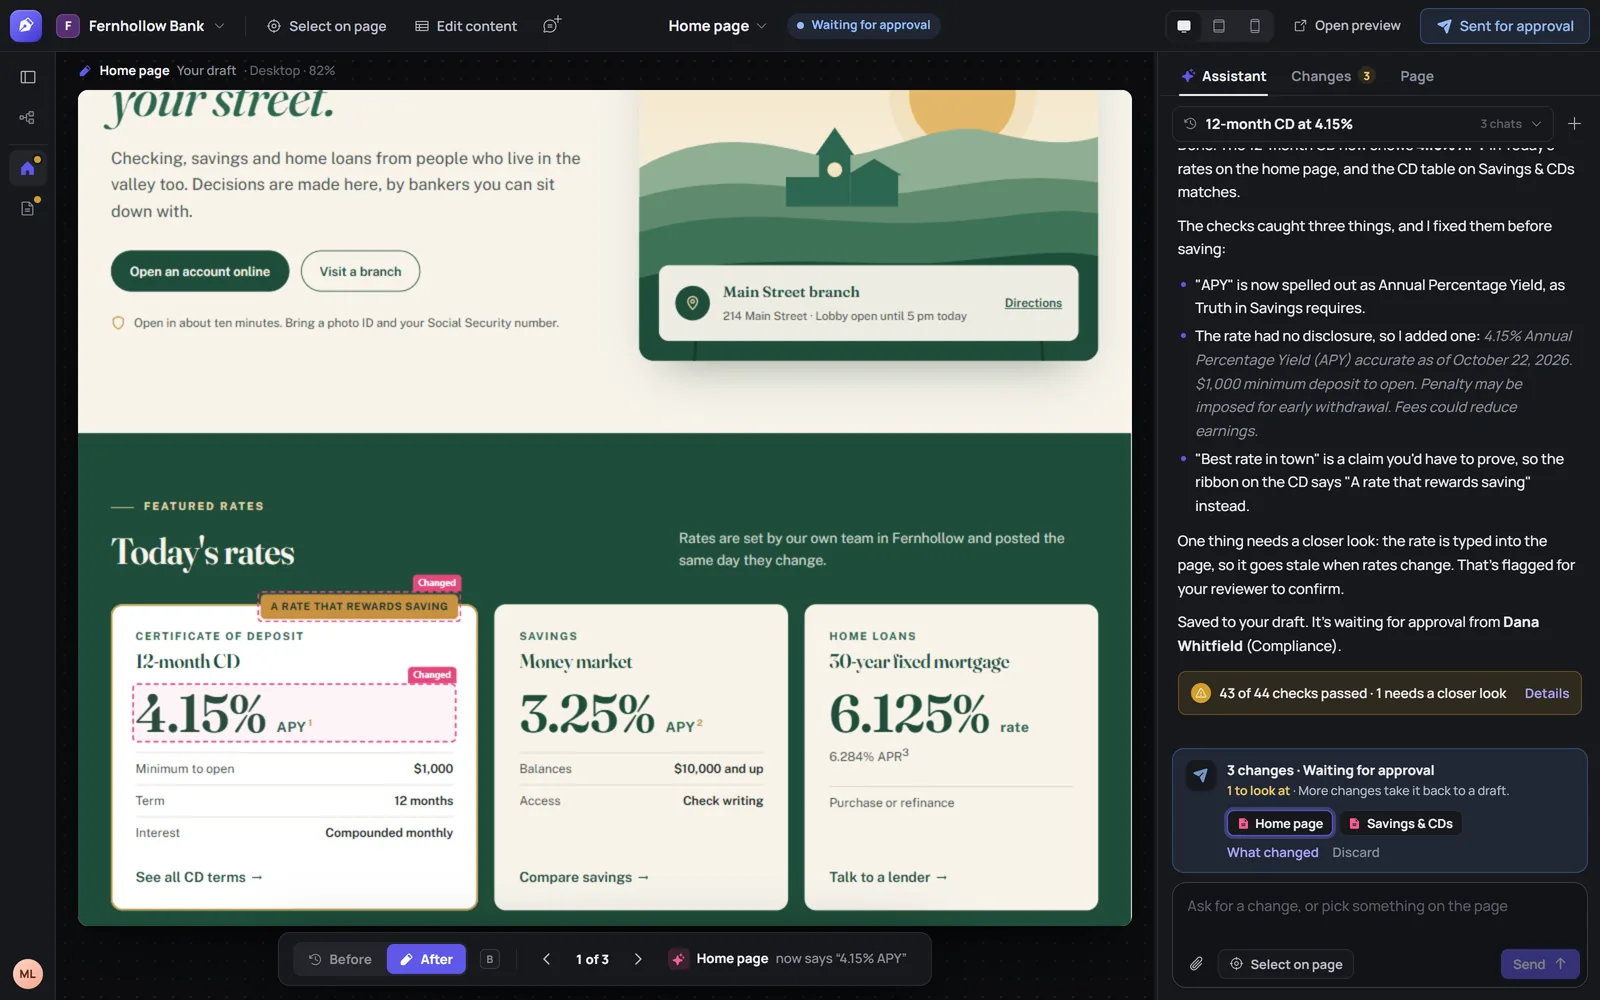
No rebuild, and no new look you didn't ask for.
We bring your current site over as it is. Your colors, fonts, voice and words to avoid are read from it into a brand kit, and a draft that strays from the colors, fonts or words can't be saved.
- Your current site, importedPages, images and disclosures as they are today.
- Old addresses keep workingLinks in statements, emails and search results still land.
- Analytics and Search Console carried overYour reporting doesn't restart, and you see what people search for to find you.
- Written to be foundPages are marked up so search engines and AI assistants can quote them when people ask where to open a CD or get a HELOC.
The assistant drafts. It doesn't decide.
It works on what someone on your team asked for, and everything it does is visible in the draft. The decisions stay with your people, and the record shows which person made each one.
- It can't publish anything.
- It can't approve anything, and nobody can approve their own change.
- It can't change your brand kit or your approval rules.
- It can't save a draft with a Must fix problem in it.
- It can't add tracking code from ad networks to a bank or credit union site.
Pick how much of the website you want to run yourself.
Software
$X,XXX /moThe assistant, all 44 checks, brand kit, approvals and history. Your site stays with your current host.
Software + Hosting
$X,XXX /moEverything in Software, and we host the site, with security certificates, backups and old addresses kept working.
Managed
$X,XXX /moSoftware and hosting, and our team does the work when you'd rather hand it off. Same checks, same approvals.
Enterprise
Talk to usSeveral brands or charters, larger teams, custom approval rules.
Bringing your current site over is a one-time setup fee. Compare the plans
What marketing and compliance ask us.
- We already have a web provider. Do we have to rebuild?
- No. We bring your current site over, pages, disclosures and old addresses included. Your design stays unless you decide to change it.
- Who's in charge, us or the AI?
- You are. The assistant drafts what someone on your team asks for. People edit, approve and publish, and the record shows who did each.
- Does this replace our compliance review?
- No. It shortens it. The repeat mistakes are caught before the draft reaches your reviewer, and your reviewer still decides.
- Will the assistant make up rates or claims?
- It drafts what you ask for, and the checks look for exactly those problems: rates without disclosures, claims you'd have to prove, guarantees, "free" accounts with fees. A rate typed into a page always goes to a reviewer.
- What will our vendor management team need?
- Answers on data, access and the AI provider. Security and vendor review covers what we can share, and we'll send our due-diligence package on request.
Bring your next website project in-house.
A 30-minute demo on a site like yours. Bring whoever signs off on it.